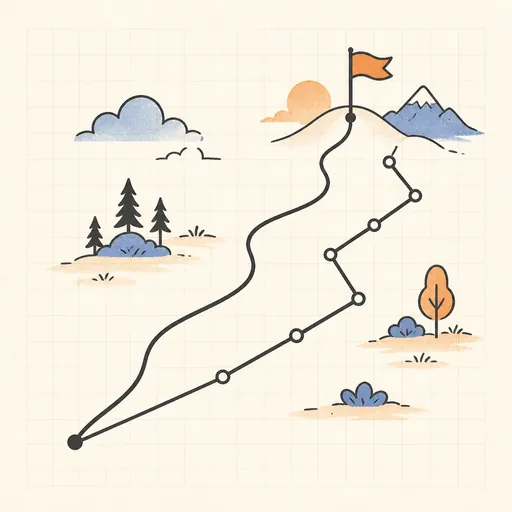
Euler vs Runge–Kutta
Numerical ODE solvers step along a solution using only slope evaluations — and how they use them matters enormously. This demo integrates the same differential equation with Euler’s one-slope step and the classic four-stage Runge–Kutta method, plotting both against the exact solution. Drag the step size h and watch Euler’s curve peel away while RK4 hugs the truth even at coarse steps; the displayed global errors shrink like h for Euler but like h⁴ for RK4.
Runs 100% in your browser — simulations are computed locally on your device.
Read the full guide to this tool
Notes
- Euler: y ← y + h·f; one slope per step, global error O(h).
- RK4 blends four slope samples per step for global error O(h⁴) — halving h cuts the error 16-fold.
- For stiff equations even RK4 struggles; implicit methods take over there.
- Runs 100% in your browser — simulations are computed locally on your device.
Related tools
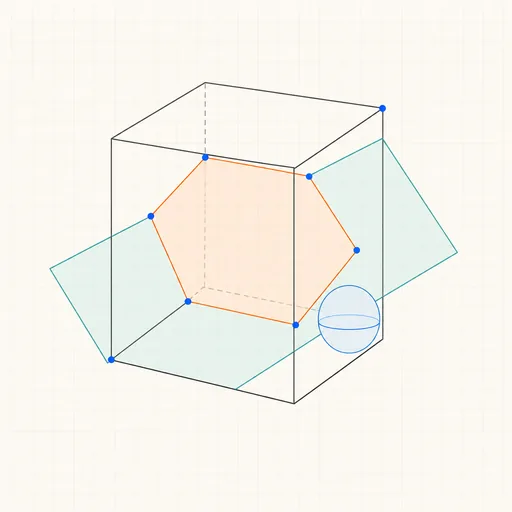
3D Geometry Board
Points, lines, planes, spheres and polyhedra on an orbiting camera — slice solids with planes, unfold nets, drop the Dandelin spheres into a cone and drag everything.
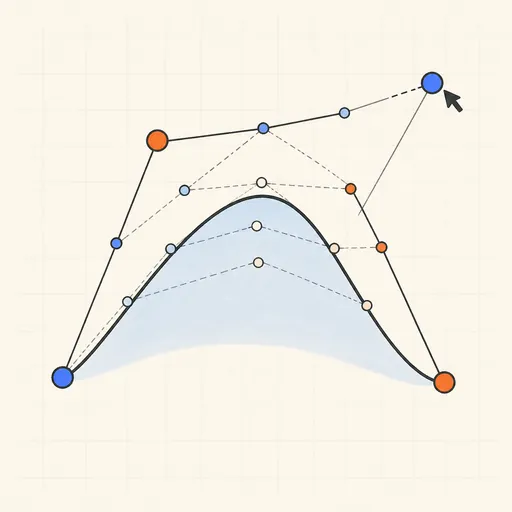
Bézier Curve Playground
Drag control points and watch De Casteljau’s algorithm construct a Bézier curve step by step.
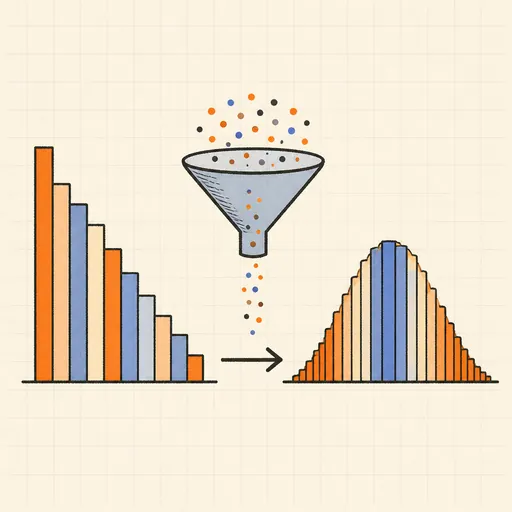
Central Limit Theorem Demo
Sample from any lopsided distribution and watch the averages pile up into a bell curve.
Conway’s Game of Life
Paint cells and watch Conway’s cellular automaton breed gliders, guns and oscillators.
Dynamic Geometry Board
Construct with points, lines, circles and transformations, then drag anything — the construction stays true, and a checker tells you which relations are theorems.
Fantasy Map Generator
Roll a seed and get a continent: coastlines, mountains, rivers, biomes and named towns, ready for your campaign.