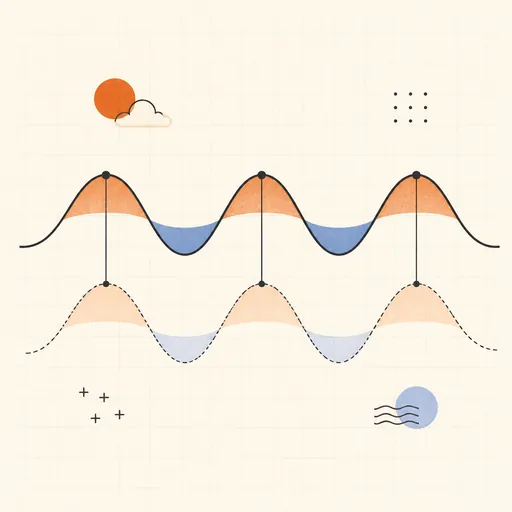
Autocorrelation Calculator
Computes the autocorrelation function of a time series: the correlation of the series with itself shifted by 1, 2, … lags. Values outside ±1.96/√n suggest real serial dependence, and the Ljung–Box test aggregates all lags into one verdict — the standard check for whether residuals are white noise.
Read the full guide to this tool
Results
Notes
- rₖ near +1 at lag k means the series repeats its pattern every k steps; trending data shows slowly decaying positive ACF.
- For white noise about 5% of lags will poke outside the band by chance alone.
- The Ljung–Box statistic is χ²-distributed with one degree of freedom per lag tested.
Related tools
Descriptive Statistics Calculator
Mean, median, quartiles, variance, skewness, outliers and more.
Kaplan–Meier Survival Calculator
Survival curve, life table and median survival from time-to-event data with censoring.
Outlier Detector
Grubbs' test, Tukey fences and z-scores on your data.
Time Series Lab: Decomposition, ETS & ARIMA Forecast
Paste a CSV: seasonal decomposition, ETS and ARIMA fits, forecast intervals and rolling-origin cross-validation.
Covariance Calculator
Sample and population covariance with Pearson correlation.
Percentile Calculator
Find the value at a percentile, or the rank of a value.