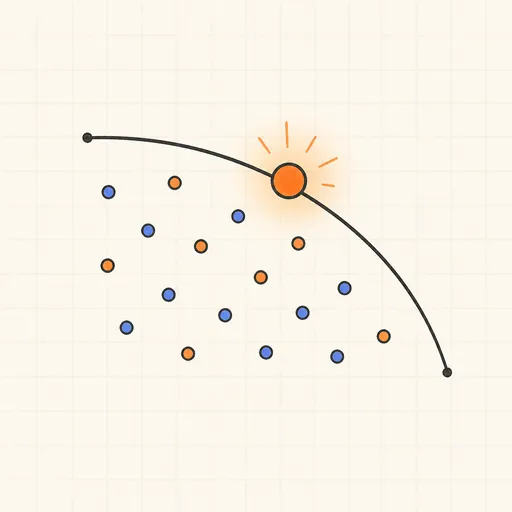
Efficient Frontier & Rebalancing Bonus
Builds the Markowitz efficient frontier for a small set of assets from your expected returns, volatilities and pairwise correlations. It samples 2000 random long-only portfolios to show the cloud of possibilities, traces the frontier of minimum-risk portfolios along it, and solves for the two classic corner portfolios: minimum variance and maximum Sharpe ratio (best excess return per unit of risk above your risk-free rate). It also estimates the “rebalancing bonus” — the extra geometric return an equal-weight, regularly rebalanced mix earns over the average of its parts, roughly half the variance you diversify away.
Read the full guide to this tool
Results
Notes
- The frontier is only as good as its inputs — expected returns are guesses, and small changes in them move the optimal weights a lot.
- Low or negative correlation is the free lunch: it lets the portfolio be calmer than any of its parts.
- The rebalancing bonus ≈ (average variance − portfolio variance) / 2 — harvesting it requires actually selling winners to buy losers on a schedule.
- Long-only weights are assumed; with short selling the frontier extends further but the math and the risks change.
- This is an educational estimate, not financial advice; talk to a qualified adviser before making money decisions.
Related tools
CAGR Calculator
Compound annual growth rate between two values.
Dollar-Cost Averaging Calculator
Project a regular investing plan’s future value.
Investment Growth Calculator
Portfolio projection with monthly contributions.
Options Strategy Lab
Build multi-leg option strategies and see the payoff curve, Greeks and probability of profit update live.
ROI Calculator
Return on investment, simple and annualized.
Capital Gains Tax Calculator
Profit and tax on a sold investment.